Learn
A lower price or a seller credit?
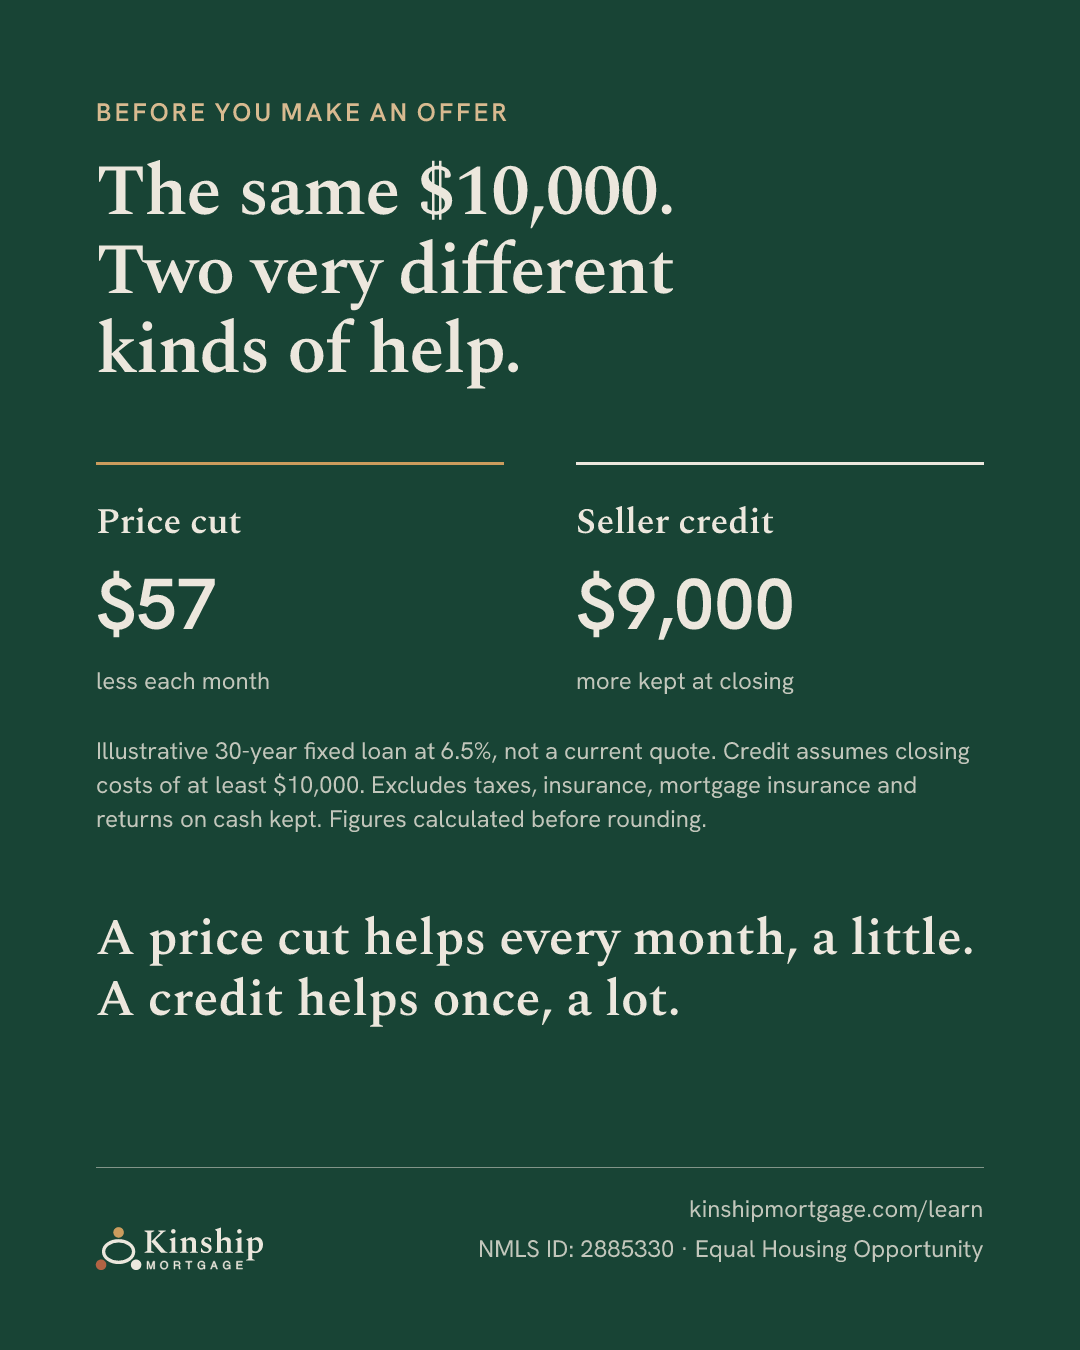
A price cut lowers your monthly payment a little, every month. A seller credit lowers the cash you need at closing a lot, once. Ask for the one that eases whatever is tighter for you.
The short version
When a seller is ready to give up $10,000, a lower price feels like the obvious choice. It’s the number everyone sees, and it’s the number you’ll remember.
But the same $10,000 can reach you in two very different ways. One arrives as a small saving every month. The other arrives all at once, on closing day.
01 · The price cut
A price cut shrinks the loan, so it lowers the payment, but only slightly.
Take a $400,000 home with 10% down. Cutting the price to $390,000 lowers the down payment by $1,000 and the loan by $9,000. The loan is repaid over 30 years, so that $9,000 comes back to you in small monthly pieces.
02 · The seller credit
A seller credit pays closing costs, so it lowers your cash to close almost dollar for dollar.
Keep the price at $400,000 and ask the seller to put $10,000 toward your closing costs instead. The loan stays the same, but you bring $10,000 less to the table, or $9,000 less than with the price cut.
The same $10,000, two ways · $400,000 home, 10% down
| $10,000 price cut | $10,000 seller credit | |
|---|---|---|
| Monthly principal and interest | $2,219 | $2,275 |
| Less cash at closing | $1,000 | $10,000 |
The price cut saves about $57 a month. The credit saves $9,000 more on closing day. At $57 a month, catching up takes about 13 years.
A credit has limits a price cut doesn’t.
A seller credit can pay closing costs and prepaid items, but not your down payment, and it can’t be more than your actual costs. Loan programs also cap it. On most conventional loans for a home you’ll live in, the cap is 3%, 6% or 9% of the purchase price or appraised value, whichever is lower, depending on how much you borrow compared with the home’s value. Investment properties have a lower cap. FHA and VA loans follow their own rules. Any credit also needs to appear in the purchase contract, so decide before you make the offer, not after.
03 · Your decision
Ask for the one that eases what is tighter for you: the monthly budget or the cash.
Three questions help. Talk them through with your agent before you write the offer.
- Is cash or the monthly payment the tighter constraint?
- If closing day would leave your savings thin, the credit usually does more for you. If the payment is at the edge of comfortable, look harder at the price.
- How long do you expect to keep this loan?
- The price cut's monthly saving only overtakes the credit after years. If you might sell or refinance sooner, the credit's advantage holds.
- Will your loan program allow the full credit?
- Check the cap for your program and down payment, and whether your closing costs are large enough to absorb it. The home also still has to appraise at the full price. Some buyers use part of a credit to pay for a lower rate. That is a different tradeoff, so compare it with a quote.